Money as a couple: Is wedding insurance worth it? What it covers
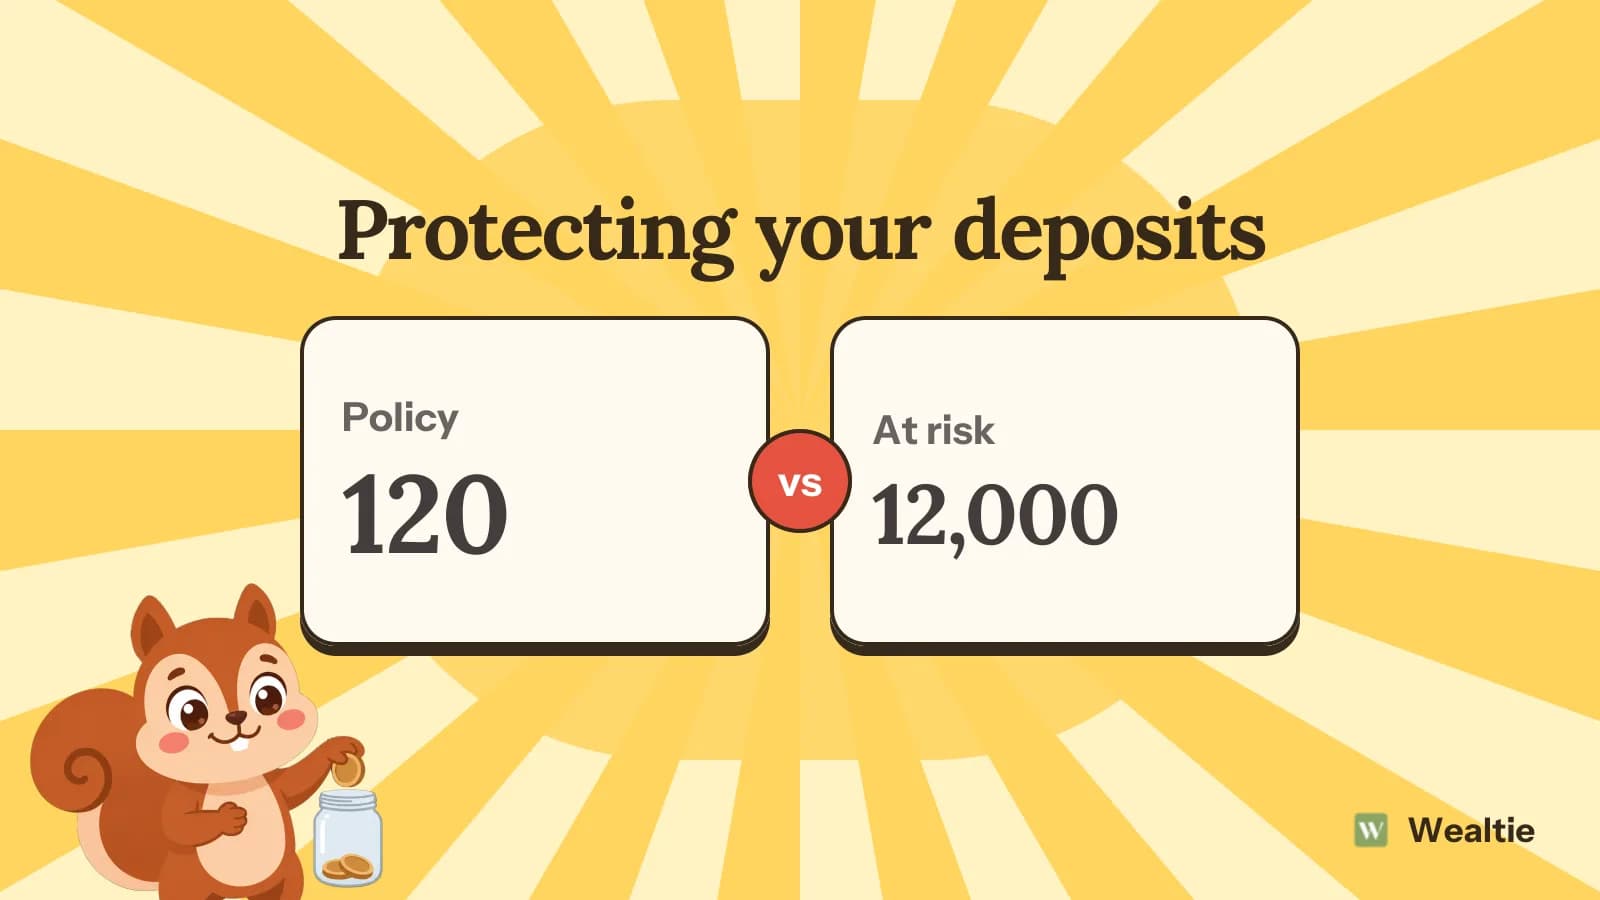
Is wedding insurance worth it? It is when you've paid large deposits you'd lose if a supplier failed or the day had to move, and in a worked example, 120 protects 12,000 of payments.
 By Wealtie Team · 3 min read
Key takeaways
- Wedding insurance protects money already paid if suppliers fail or the day must move.
- It's most useful when large deposits are paid months in advance.
- Change of heart and known problems are usually excluded.
- Paying suppliers by credit card can add another layer of protection.
What is wedding insurance?
Wedding insurance protects the money you've spent on your wedding if something goes wrong that's out of your control. Most policies cover cancellation or postponement for reasons like serious illness, bereavement or extreme weather, supplier failure if a venue or caterer goes out of business, and damage or loss of items like the dress, rings and gifts. Some include public liability cover, which certain venues require.
Because weddings involve paying large deposits months or even years in advance, a lot of money can be at risk before the day. Insurance costs a small fraction of that and can help you rebook or recover costs if plans fall through.
How much money is at risk?
Here's a worked example of deposits and payments made by a few months before the wedding, in round numbers that work in any currency:
| Paid in advance | Amount |
|---|---|
| Venue and catering deposits | 7,000 |
| Photographer and band | 2,500 |
| Dress and suits | 1,500 |
| Flowers, cake and other suppliers | 1,000 |
| Total | 12,000 |
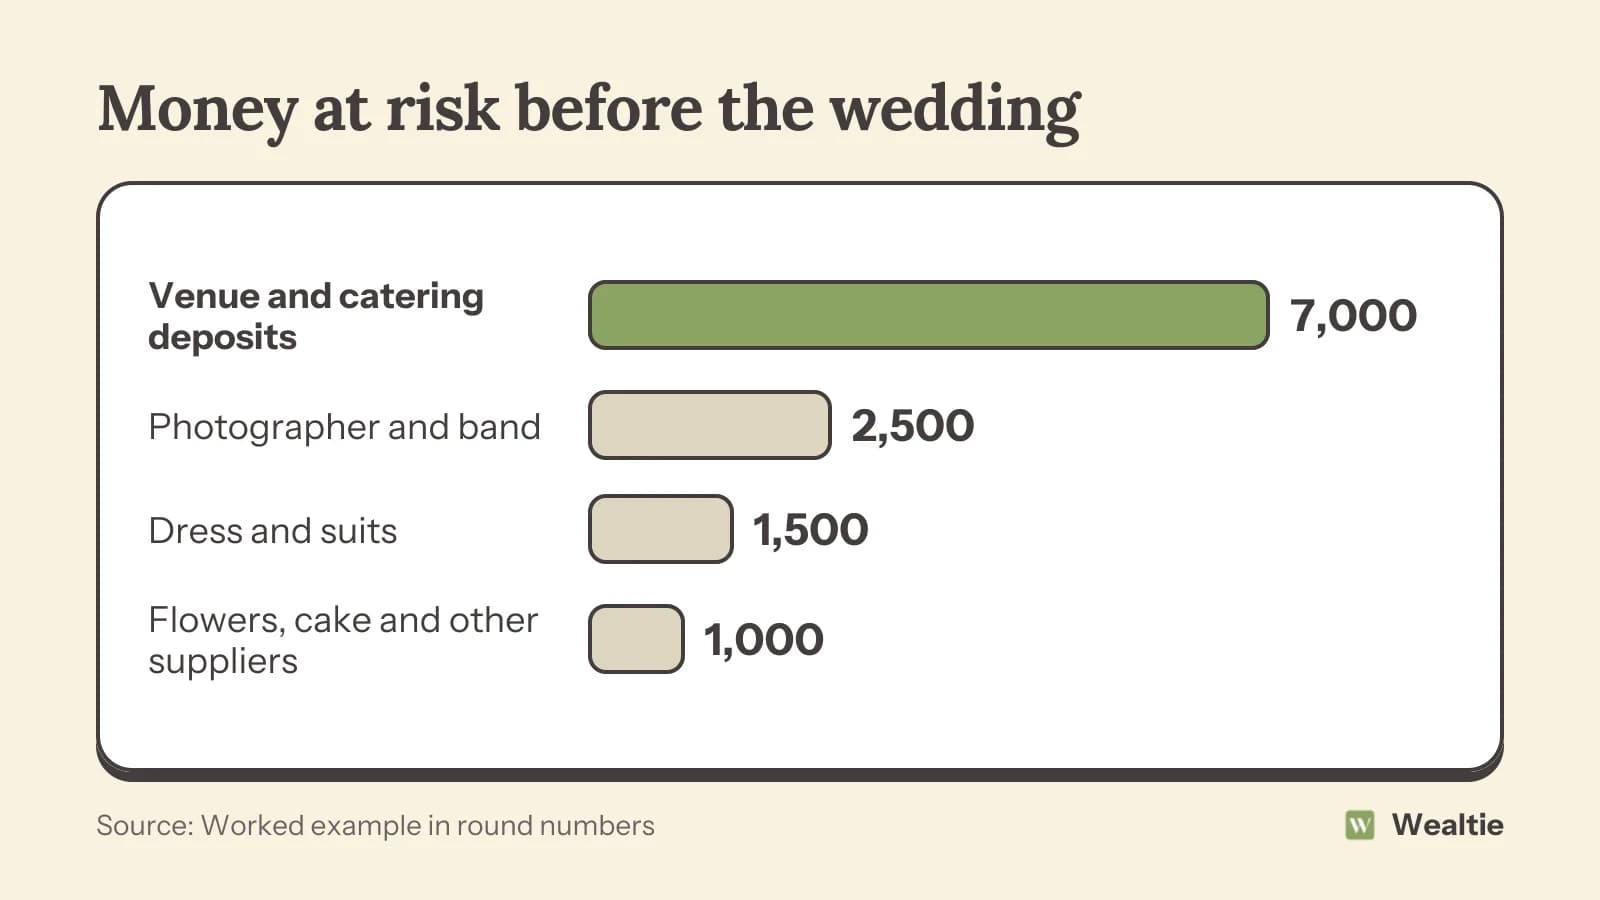
A policy covering that amount might cost around 120, depending on the level of cover and where you live. If the venue went out of business or a close family member fell seriously ill and you had to postpone, the policy could pay back lost deposits or the extra cost of rebooking.
Is wedding insurance worth it?
When it's worth it
Insurance is most useful when you've paid large deposits early, especially to a single venue or supplier. It's also worth considering for destination weddings, weddings with elderly or unwell close relatives, or venues and suppliers that are small businesses.
When you might skip it
If your wedding is small and most of the costs are paid close to the date, or your suppliers offer flexible terms, there's less money at risk. Some couples decide the cost isn't needed.
What it won't cover
Insurance won't pay out if you change your mind or call off the wedding by choice. It usually excludes problems you knew about when you bought it, like a relative's existing illness, and may exclude some weather or travel disruption. Read the terms closely.
What should you check in a policy?
Cancellation and postponement reasons
Check exactly which events are covered, like illness, bereavement, supplier failure, venue damage or extreme weather.
Cover limits
Make sure the cancellation limit covers what you've paid and will pay. Some cheaper policies have low limits.
Supplier failure
Check that it covers suppliers going out of business, not just failing to turn up.
Excess
Most policies charge an excess on each claim.
When to buy
Buy cover as soon as you start paying deposits, since policies usually only cover problems that arise after you buy them.
What other protection do you have?
Supplier contracts
Read each contract's cancellation and postponement terms. Some suppliers will move dates for free, while others keep deposits.
Credit card payments
In some countries, paying by credit card gives you extra protection if a supplier fails to deliver. Check the rules where you live.
Travel insurance for destination weddings
For weddings abroad, travel insurance for you and your guests covers different risks, like missed flights and medical costs. Is travel insurance worth it? covers what to look for.
How does it fit into the wedding budget?
Add insurance as its own small line in your wedding budget, alongside the venue and suppliers. It's a small cost compared with the total, and planning it early means you're covered as soon as deposits are paid. Which insurance do you need? covers how to think about insurance more generally.
Keep all your contracts, receipts and emails with suppliers in one folder, along with the policy documents. If you ever need to claim, insurers will ask for evidence of what you paid and what the supplier agreed to provide, and having it all in one place makes the process much quicker and less stressful at an already difficult time.
It's also worth talking to your suppliers early about what would happen if the date had to move. Many are flexible and will transfer deposits to a new date at no cost, which reduces how much you'd need to claim. Knowing their policies helps you choose the right level of cover.
If you're paying for most things close to the date, ask whether a smaller policy with lower limits would cover what's at risk. That keeps the cost proportionate to the money you'd lose.
How can Wealtie help you track wedding payments?
Set a budget for the wedding and log every deposit and payment in its own expense category. Keeping a clear record of what you've paid, to whom and when also makes an insurance claim much easier if you ever need one.
Questions people ask
It's worth it when you've paid large deposits in advance that you'd lose if a supplier failed or the wedding had to be postponed.
Policies often cover cancellation or postponement for illness, bereavement or extreme weather, supplier failure and loss or damage of items like rings and the dress.
No. Wedding insurance doesn't pay out if you decide to call off the wedding by choice.
Buy it as soon as you start paying deposits, since policies usually only cover problems that arise after you buy them.
This article is general information, not financial, tax or legal advice. Your situation is your own; check the numbers that apply to you before you act on them.